 Money in One Chart
where money goes
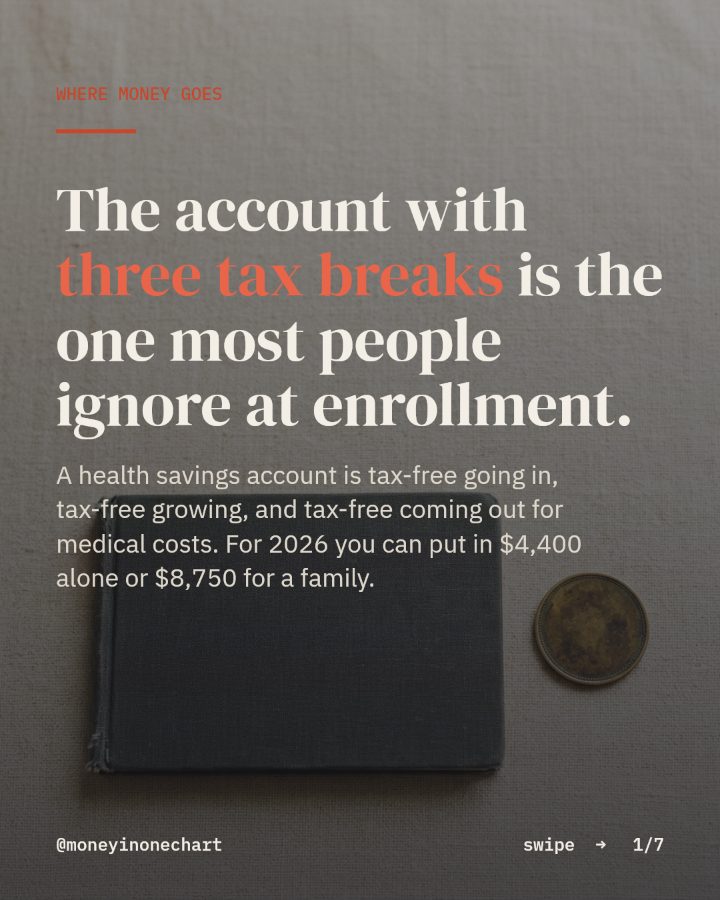
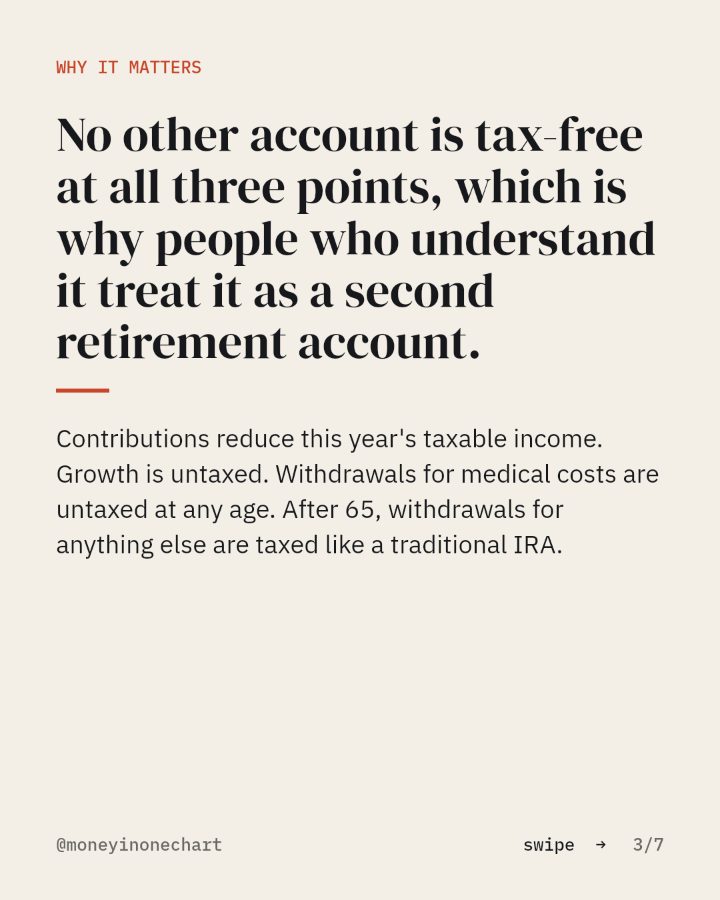
The account with three tax breaks is the one most people ignore at enrollment.
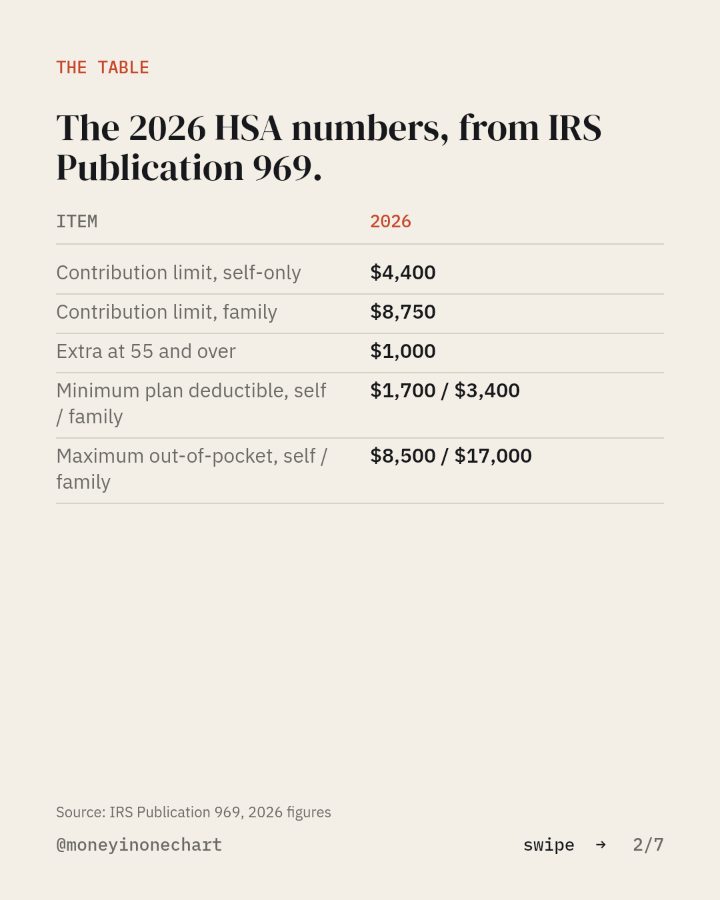
A health savings account is tax-free going in, tax-free growing, and tax-free coming out for medical costs. For 2026 you can put in $4,400 alone or $8,750 for a family.
You asked for the HSA checklist. It is below, as the slides from the post, then the one move, then the tool the chart points at.
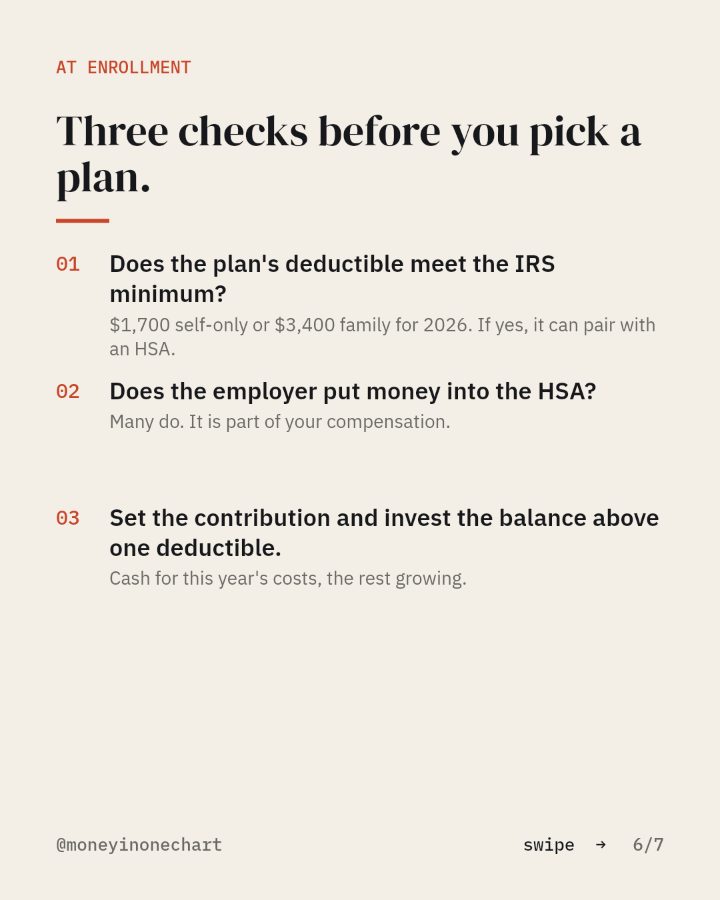
Three checks before you pick a plan.
- 01Does the plan's deductible meet the IRS minimum?$1,700 self-only or $3,400 family for 2026. If yes, it can pair with an HSA.
- 02Does the employer put money into the HSA?Many do. It is part of your compensation.
- 03Set the contribution and invest the balance above one deductible.Cash for this year's costs, the rest growing.
The tool this chart points at
A low-fee brokerage
For the IRA, the index fund and the rollover. Broad index funds with expense ratios under 0.1%.
Open itThis link may pay Money in One Chart a referral fee if you open an account. Your price does not change. How that works.
Sources: IRS Publication 969, 2026 figures.